Global trade supply chains are being rebuilt around resilience as exporters face overlapping shocks from geopolitics, tariffs and tighter financing conditions. Allianz Trade’s latest Global Survey of 6,000 firms signals steady demand but thinner buffers, forcing networks, payment terms and risk tools to adapt together.
Trade Growth On a Higher-Risk Footing
Export demand prospects remain firm despite a harsher operating climate. Three quarters of surveyed exporters still expect overseas sales to expand into 2026, even as global GDP growth is projected near 2.6 percent and inflation stays above 4 percent. That confidence stands in contrast to 2025, when a major US tariff round often labelled Liberation Day drove a 40 point drop in export optimism and exposed how sensitive flows had become to policy shocks.
The backdrop has shifted from isolated crises to a persistent risk baseline. Around 65 percent of companies now rank geopolitical and political tension as their top concern, pushing supply chain complexity into third place. Direct supply issues such as supplier insolvency and input shortages have moved into second, reflecting insolvency levels that remain above pre pandemic norms in many markets. Allianz Trade estimates the economic drag from network complexity at about 4.7 trillion US dollars in 2025, more than double the cost recorded in 2017 and heavily concentrated in US-linked trade lanes.
Logistics and energy sit at the center of this risk repricing. Six in ten respondents highlight vulnerability to shipping disruption and swings in energy and commodity prices, with exposure highly uneven by country. Firms in Vietnam, Poland, the United Kingdom and the United States report elevated concern, while companies in India and China appear somewhat better cushioned by broader supplier bases, alternative routes and in some cases stronger financial buffers.
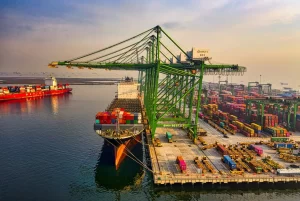
These pressures are reshaping day to day network design. More than half of surveyed firms are already switching carriers or reconfiguring routes in response to chokepoints such as the Strait of Hormuz and Red Sea corridors, where even optimistic scenarios suggest only gradual normalisation. Many are working more closely with customs brokers to compress border dwell times and are resequencing delivery windows to create more room for disruption. Routing changes and process workarounds are spreading faster than formal contract resets, which raises the bar for control towers and digital twins that can test options and costs in near real time.
Finance, Terms and Technology Tighten The System
Risk is also moving from physical flows into financial terms. As global liquidity tightens and borrowing costs remain elevated, 43 percent of exporters expect payment terms to lengthen or otherwise deteriorate in the coming year. Concerns about non payment are rising, especially in capital intensive segments such as construction, technology hardware and pharmaceuticals, where long lead times and high working capital needs magnify counterparty failure.
Contract structures are being rebalanced to reflect this shift. Four out of five firms have adjusted trade or logistics routes to reduce tariff exposure or avoid geopolitical hotspots, even with average US tariff rates still close to 9 percent. At the same time, delivery conditions are being rewritten: exporters are trimming the use of Delivered Duty Paid terms that leave them responsible for duties and last mile logistics in volatile markets, while importers lean toward Free On Board clauses to take earlier control of freight, routing and customs risk. These moves require tighter alignment between trade finance, risk teams and front line logistics operations.
De risk strategies have moved into the mainstream. Companies are building targeted inventory buffers, diversifying end markets, onboarding new suppliers and in some cases routing goods via third countries to navigate tariff schedules and sanctions. Industry reports show similar patterns in nearshoring and friendshoring programs, where additional nodes and partners absorb shocks but add more moving parts. The task now is to move from a patchwork of local fixes to coherent network designs that balance cost, service and volatility.
The Allianz Trade survey also surfaces a divided picture on environmental, social and governance priorities and on artificial intelligence. Overall ESG commitment has dropped sharply since 2025, with pronounced declines in China and the United Kingdom, while firms in Germany and parts of Europe sustain higher engagement, supported by regulatory frameworks such as the EU Corporate Sustainability Reporting Directive. This divergence creates friction for global networks that must reconcile differing carbon, due diligence and reporting expectations while keeping logistics and procurement competitive.
AI adoption is more advanced but uneven in depth. Most exporters now use AI in some aspect of operations, from demand forecasting and document handling to risk screening on suppliers and routes. Uncertainty over return on investment remains the main brake on broader deployment. Experience from early adopters indicates that AI delivers tangible value when tied directly to cash and service metrics such as days sales outstanding, lead time variability and inventory turns, rather than treated as a technology experiment.
A New Balance Between Risk, Liquidity and Reach
The survey highlights a quieter shift sitting underneath tariff headlines and freight disruptions: the redistribution of risk and liquidity along global trading relationships. As payment terms stretch, delivery clauses change and freight is rerouted, working capital and exposure increasingly migrate toward those with the strongest data, risk infrastructure and access to funding. Networks that invest early in joined up trade risk, supply and finance visibility will set the operating norms others must match, not just react to, as the next phase of globalisation takes shape.