A majority of large companies now see an agile, sustainable, AI-driven “new-gen” supply chain as a strategic priority, according to new research from the Capgemini Research Institute. In a survey of 1,000 senior executives across 13 countries and four sectors, 70% ranked the new-gen supply chain among the top three tech trends for 2025. The share of organizations reporting significant supply chain change has climbed from 54% in 2022 to 72% in 2025, and 68% say they’ve established a clear vision and objectives for their networks.
AI Agents Shift From Pilots to Productivity
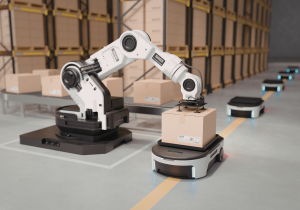
Capgemini finds momentum shifting from proofs of concept to operating impact. Two-thirds (67%) of executives believe agentic AI will boost productivity, and 58% say it will transform existing frameworks and processes. Early deployments span forecasting, inventory management, logistics routing, and multi-tier risk sensing, often coupled with supply chain control towers, digital twins, and IoT feeds to act on signals in near real time.
The report stresses a human-centered rollout: agentic systems need strong governance, integration with existing information platforms, and clear oversight to prevent automation from reinforcing bad data or biased decisions. Recent trade reports echo this, noting that AI gains tend to scale fastest where firms have already rationalized master data and harmonized planning calendars across commercial and operations teams.
Sustainability and Security Become Cost Levers
Sustainability moves are no longer framed as compliance alone. Three-quarters (76%) of organizations say they have a comprehensive supply chain sustainability strategy, and more than three-quarters agree that sustainable practices reduce costs and create long-term value. According to sector analyses, initiatives such as route optimization, energy-aware operations, circular design, and better waste control are yielding measurable savings while improving Scope 3 visibility. At the same time, security and policy exposure are sharpening operational choices. Cyber risk tops the obstacle list, pushing investment in real-time monitoring and standardized protocols across suppliers.
Tariff sensitivity is also rising, with companies diversifying suppliers and manufacturing footprints, redesigning products to lower-duty components, and using trade mechanisms like FTAs and foreign-trade zones to protect margins. Recent policy and sustainability reporting trends, such as European product passport efforts and expanded emissions disclosures, are accelerating data capture at the item and supplier level, which many firms are now turning into decision inputs, not just audit trails.
Where the Next Battle Will Be Fought
The coming pressure point is not just in deploying AI or broadening supplier networks but in how effectively companies treat compliance and policy data as operational currency. With European digital product passports, U.S. tariff adjustments, and expanding emissions disclosures, much of the data infrastructure is being mandated anyway. The real test will be which firms build the mechanisms to turn those same requirements into live inputs for sourcing, routing, and pricing decisions, shifting compliance from a reporting burden into an everyday competitive tool.