The last mile has quietly become the most scrutinized and least forgiving segment of the supply chain. What was once treated as a downstream execution problem is now a core driver of customer experience, cost-to-serve, and operational resilience. Recent data shows that last mile delivery trends are no longer just about speed or convenience. They are about control, cost discipline, and the ability to scale service without relying on expensive workarounds.
As networks become more fragmented and demand variability increases, organizations are being forced to rethink how they design last mile operations. The shift is not about incremental optimization. It is about fundamentally changing how delivery capacity is sourced, managed, and measured.
Why last mile delivery trends are shifting from speed to control
For years, the dominant narrative in last mile logistics focused on faster delivery windows. Same-day and next-day services became competitive benchmarks, often at the expense of margin discipline. That model is now under pressure.
The core issue is structural. The last mile accounts for more than half of total logistics costs in many distribution networks, and in some sectors it can exceed 60 percent. This makes last mile logistics cost one of the most sensitive levers in overall supply chain performance. Yet many organizations still manage it with limited visibility and reactive decision-making.
What is changing now is the shift toward control-based models. Instead of optimizing individual deliveries, companies are investing in systems and processes that allow them to manage variability at scale. This includes:
- Real-time delivery orchestration across multiple carriers
- Dynamic routing based on capacity and cost thresholds
- Improved exception management to reduce manual intervention
- Integration of fulfillment and delivery planning to avoid downstream disruptions
This shift is not theoretical. According to trade reports, companies that invest in centralized control tower capabilities are reducing expedited freight and improving delivery reliability without increasing cost.
Another emerging trend is the move toward delivery promise accuracy rather than simply faster delivery. Customers are becoming more tolerant of slightly longer delivery windows if those windows are consistently met. This has direct implications for cost. By stabilizing lead times, organizations can reduce reliance on premium shipping options and improve route efficiency.
A less discussed but equally important trend is the growing role of data quality in last mile performance. Many delivery inefficiencies stem from poor address data, inaccurate order information, or lack of integration between order management and transportation systems. Fixing these upstream issues often delivers more value than investing in additional delivery capacity.
In practical terms, the companies making progress are not those chasing faster delivery. They are the ones reducing variability and improving predictability.
Regional carrier vs FedEx UPS: a structural shift in network design
One of the most significant developments in last mile delivery trends is the reassessment of carrier strategy. The traditional model relied heavily on national carriers such as FedEx and UPS, valued for their scale, reliability, and standardized service.
That model is being challenged. The comparison between regional carrier vs FedEx UPS is no longer just about price. It is about network fit, flexibility, and risk distribution.
Regional carriers are gaining traction for several reasons:
- Cost efficiency on specific lanes
Regional carriers often offer lower rates within defined geographic areas. For high-density delivery zones, this can significantly reduce last mile logistics cost without compromising service levels.
- Capacity flexibility
During peak periods, national carriers tend to impose surcharges or capacity limits. Regional providers can offer more flexible arrangements, particularly for short-haul and urban deliveries.
- Service customization
Regional carriers are typically more willing to adapt to specific delivery requirements, such as time windows, specialized handling, or customer-specific processes.
However, the shift toward regional carriers introduces new complexities. Managing multiple carriers increases operational overhead, particularly in areas such as contract management, performance tracking, and system integration.
This is where many organizations struggle. The theoretical benefits of a multi-carrier strategy are clear, but execution often falls short due to lack of governance and visibility. The key trade-off is between simplicity and optimization.
- A single national carrier offers simplicity, standardized processes, and easier management
- A multi-carrier network, including regional providers, offers cost savings and flexibility but requires stronger operational discipline
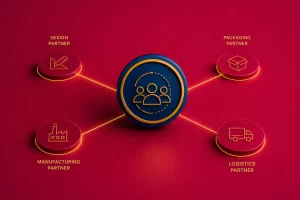
Recent data shows that hybrid models are becoming the norm. Organizations are not replacing national carriers entirely. Instead, they are segmenting their network:
- National carriers for long-haul and low-density routes
- Regional carriers for high-density urban and regional lanes
- Specialized providers for same-day or time-critical deliveries
This segmentation allows companies to align carrier selection with specific lane characteristics rather than applying a one-size-fits-all approach.
Another important factor is resilience. Over-reliance on a single carrier increases exposure to disruption, whether due to capacity constraints, labor issues, or network congestion. A diversified carrier strategy reduces this risk but only if it is supported by strong coordination mechanisms.
Technology plays a critical role here. Transportation management systems and delivery orchestration platforms are enabling organizations to manage multi-carrier networks more effectively. However, the value of these tools depends heavily on how they are implemented and governed.
One common mistake is treating technology as a solution rather than an enabler. Without clear decision rules, performance metrics, and ownership structures, even the most advanced systems fail to deliver meaningful improvements.
Cost pressure is forcing a rethink of last mile economics
The rising focus on last mile logistics cost is not just a response to inflation or fuel prices. It reflects a deeper realization that traditional delivery models are not sustainable at scale. Several cost drivers are converging:
- Increased customer expectations for faster delivery
- Higher labor costs and driver shortages
- Urban congestion and regulatory constraints
- Rising fuel and vehicle maintenance expenses
These pressures are forcing organizations to rethink how they approach last mile economics. One emerging approach is cost-to-serve segmentation. Instead of offering uniform delivery options to all customers, companies are differentiating service levels based on profitability and strategic importance.
For example:
- Premium customers may receive faster delivery options
- Standard customers may be offered consolidated or scheduled delivery windows
- Low-margin segments may be steered toward cost-efficient delivery options
This approach requires a level of commercial alignment that many organizations lack. Delivery is often treated as an operational function, disconnected from pricing and customer strategy. Bridging this gap is critical to managing last mile costs effectively.
Another area of focus is delivery density. Increasing the number of deliveries per route is one of the most effective ways to reduce cost per drop. This can be achieved through:
- Better demand forecasting and order consolidation
- Strategic placement of inventory closer to demand centers
- Collaboration with partners to share delivery capacity
There is also growing interest in alternative delivery models, such as micro-fulfillment centers and local distribution hubs. These models can reduce delivery distances and improve efficiency, but they require careful network design to avoid increasing overall complexity.
Importantly, not all innovations deliver value. Some high-profile last mile solutions, such as autonomous vehicles and drones, remain limited in practical application. While they attract attention, their impact on mainstream logistics operations is still evolving. The more immediate gains are coming from operational improvements, better data, and smarter network design.
What separates high-performing last mile operations from the rest
While many organizations are investing in last mile improvements, the results vary widely. The difference often comes down to execution rather than strategy.
High-performing operations share several characteristics:
- Clear governance structures
Decision-making authority is well-defined, particularly in areas such as carrier selection, pricing, and service levels.
- Integrated planning processes
Delivery planning is aligned with inventory management, demand forecasting, and customer commitments.
- Robust performance metrics
Metrics go beyond basic KPIs such as on-time delivery. They include cost-to-serve, delivery accuracy, and exception resolution time.
- Proactive exception management
Issues are identified and resolved early, reducing the need for last-minute interventions.
- Continuous network optimization
Networks are regularly reviewed and adjusted based on changing demand patterns and cost structures.
In contrast, underperforming operations tend to rely on reactive processes, fragmented systems, and limited visibility. This leads to higher costs, lower service levels, and increased reliance on manual intervention.
One overlooked factor is organizational alignment. Last mile performance is influenced by decisions made across multiple functions, including sales, procurement, and operations. Without alignment, improvements in one area can create problems in another.
For example, aggressive sales commitments on delivery speed can increase costs if they are not supported by operational capabilities. Similarly, procurement decisions focused solely on cost can undermine service performance. Balancing these trade-offs requires a holistic approach rather than isolated optimization.
The real opportunity is not faster delivery, but smarter networks
The next phase of last mile evolution will not be defined by speed alone. It will be defined by how effectively organizations can design and manage their delivery networks. This includes:
- Aligning carrier strategy with network characteristics
- Using data to improve decision-making and reduce variability
- Integrating delivery with broader supply chain planning
- Building resilience through diversified capacity and flexible operations
The comparison between regional carrier vs FedEx UPS is just one example of this broader shift. It highlights the need to move beyond traditional models and adopt more nuanced approaches to network design.
Rethinking the role of last mile in supply chain strategy
The most important shift may be conceptual. Last mile delivery is no longer just the final step in the supply chain. It is a critical interface between operations and customer experience. Organizations that treat it as a strategic capability rather than a cost center are better positioned to navigate the challenges ahead.
The real question is not how to deliver faster. It is how to deliver reliably, cost-effectively, and at scale without constant firefighting. That requires discipline, clarity, and a willingness to challenge established assumptions.
Conclusion: The hidden risk in over-optimizing the last mile
There is a growing tendency to treat last mile optimization as a standalone initiative. However, focusing too narrowly on delivery can create unintended consequences. For example, pushing for maximum delivery efficiency without considering upstream variability can lead to fragile systems that struggle under disruption. Similarly, over-segmentation of carriers and services can increase complexity beyond what the organization can manage effectively.
The more sustainable approach is to view last mile as part of an interconnected system. Improvements should be evaluated not just on their local impact, but on how they affect the overall supply chain.
Recent data shows that the most resilient organizations are those that prioritize coordination over optimization. They accept slightly higher costs in some areas to achieve greater stability and predictability across the network. This perspective challenges the traditional focus on cost minimization. It suggests that the real competitive advantage lies in consistency and control, not just efficiency.